The ECGI blog is kindly supported by
Giving Investors a Voice Without Fragmenting Shareholder Power
Authors
Over the past few decades, large institutional investors have become central players in corporate governance. Their concentrated stakes have strengthened shareholder oversight through informed voting, engagement with management, and support for activist campaigns.
More recently, however, developments in the asset management industry have begun to reshape shareholder power, partly reflecting growing heterogeneity in investor preferences and beliefs. Investors differ in their views on environmental, social, and political issues, investment objectives, and assessments of which corporate policies create value. Large asset managers are increasingly adapting their investment products and stewardship activities to accommodate these differences.
One response has been the proliferation of specialized investment funds. Another, more recent development is the decentralization of stewardship, including pass-through voting programs that allow fund investors to exercise voting rights directly. The Big Three asset managers have also announced changes to their stewardship teams, moving toward more differentiated approaches to voting and engagement.
These developments can improve the representation of investor preferences. However, by fragmenting shareholder power, they may also weaken shareholder oversight.
Can investor preferences be better represented without weakening shareholder monitoring? And does the form of decentralization matter? In our paper, Fragmentation of Shareholder Power, we develop a theoretical framework to study these questions.
Fund proliferation: Why its drivers matter
Our first result concerns the proliferation of specialized funds. When technological advances or regulatory changes lower the costs of launching funds, greater competition reduces fees, weakening asset managers’ incentives to monitor portfolio companies. However, when fund proliferation is driven by stronger investor preferences for specialized portfolios, investors’ willingness to pay higher fees can offset the effects of competition and strengthen monitoring.
Importantly, this positive effect relies on new funds being launched within existing families that maintain centralized stewardship. Yet the same strong investor preferences that encourage fund proliferation can also induce asset managers to compete along a new dimension: decentralizing stewardship to give investors greater control over voting rights.
Decentralization of stewardship: A new form of competition
One prominent form of decentralization is pass-through voting, which allows fund investors to vote according to their individual preferences, especially on contentious social and political issues. By offering this option, asset managers can attract or retain investors who value having their votes aligned with their preferences.
However, decentralizing voting authority can weaken shareholder oversight. Individual fund investors typically hold small stakes and lack incentives to engage in costly monitoring. Moreover, asset managers that transfer voting authority to investors may lose some of their ability to influence companies through coordinated voting and engagement.
Our framework shows that competition among asset managers can nevertheless lead to excessive adoption of pass-through voting. Investors benefit from voting in line with their preferences, while asset managers attract investors and save on monitoring costs. Neither group fully internalizes the resulting governance costs. The decline in firm values is reflected in lower share prices, with the losses borne by initial asset owners (e.g., entrepreneurs and VC investors) who sell their shares at these lower prices.
Does the form of decentralization matter?
The trade-off under pass-through voting raises a natural question: Are there alternative ways to decentralize stewardship that better represent heterogeneous investor preferences while preserving effective shareholder oversight?
One possibility is to delegate voting and monitoring authority to individual fund managers rather than directly to fund investors. Specialized fund managers can vote according to their investment mandates, reflecting the preferences of their investors more closely than a centralized stewardship team. They also retain incentives to monitor companies. Specialized funds tend to hold more concentrated positions in the firms that fit their mandates, and their managers may have better firm-specific information. These advantages can offset the loss of coordination within the fund family. As a result, delegation can improve preference representation while preserving, or even strengthening, shareholder monitoring relative to centralized stewardship.
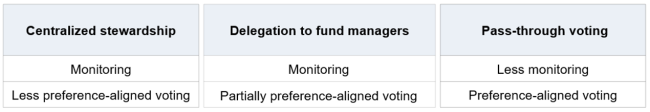
Figure 1. Three approaches to shareholder stewardship: monitoring and preference representation
Pass-through voting can therefore be less efficient than delegation to fund managers. Yet both fund investors and asset managers may prefer pass-through voting: asset managers save on monitoring costs, while investors gain from having their votes more closely aligned with their preferences. As a result, competition among asset managers may favor a less efficient form of decentralization.
Implications for the design of shareholder governance
Our findings raise broader questions about how voting and monitoring authority should be allocated to represent heterogeneous investors while preserving effective governance. Delegation to specialized fund managers is one possible approach. Other mechanisms, such as investor assemblies, surveys of investor preferences to guide asset managers' voting decisions, or pass-through voting limited to certain proposals, may also help address this trade-off.
Which of these arrangements are most effective, and will competition among asset managers lead to their adoption? Our analysis suggests that both the design of stewardship arrangements and the incentives for their adoption matter for corporate governance.
Andrey Malenko is a Professor of Finance at the Boston College's Carroll School of Management, and an ECGI Research Member.
Nadya Malenko is Tim and Debbie Connors Family Professor at Boston College, Carroll School of Management, Seidner Department of Finance, and an ECGI Research Member.
Anton Tsoy is an Associate Professor of Financial Economics at the University of Toronto, a member of the Finance Theory Group, and a research affiliate at CEPR FE.
This blog is based on a paper presented at the Corporate Governance Academic Forum at the University of Toronto with ECGI, held on 2 October 2026. Visit the event page to explore more conference-related blogs.
The ECGI does not, consistent with its constitutional purpose, have a view or opinion. If you wish to respond to this article, you can submit a blog article or 'letter to the editor' by clicking here.